
St. Cloud FL Rental Rates & Vacancy: Q3 2026 Investor Guide
Most investor conversations about Osceola County start and end within a few miles of the Disney gates. Champions Gate, Reunion, and the Davenport corridor absorb the attention because short-term rental math is loud — big gross revenue numbers, heavy turnover, real volatility. St. Cloud sits roughly twenty-five minutes east of that corridor and plays a completely different game.
For investors who would rather have tenants who renew than guests who check out, St. Cloud is one of the least-analyzed submarkets in Central Florida. Here is where rents, vacancy, and pricing actually stand as Q3 2026 closes — and, more usefully, what those numbers do to a real acquisition once you put them on a spreadsheet.
Why St. Cloud Doesn't Trade Like the Disney STR Corridor
The single most important fact for anyone underwriting a St. Cloud property is that it is not a short-term rental market. St. Cloud is an incorporated city with its own zoning code, and residential nightly rentals are not a permitted use across the bulk of its neighborhoods. Osceola County's transient-rental overlay — the mechanism that makes STR legal in the Four Corners and Highway 192 tourist corridors — does not extend into most of St. Cloud's residential districts. If a listing agent tells you a St. Cloud house "can be a vacation rental," treat that as a claim to verify with the City of St. Cloud Planning Division in writing before you close, not a feature to underwrite.
What that constraint removes in upside it returns in stability. Your demand pool is Lake Nona and Medical City commuters, Osceola County school district employees, tradespeople working the St. Cloud and Narcoossee construction pipeline, and families priced out of Lake Nona proper. Those tenants sign twelve-month leases, renew at meaningful rates, and are not sensitive to Disney attendance figures, airline capacity, or hurricane-season booking cancellations. Two very different risk profiles — and a portfolio that owns only Disney-corridor STR is more correlated than most owners realize.
What St. Cloud Rents Are Actually Doing in Q3 2026
Rent growth here has flattened into low single digits, which is the defining story of 2026 across Central Florida after several years of double-digit moves. Current market data puts the average St. Cloud apartment rent near $2,058, up about 2.8% year over year. By unit size, one-bedrooms average roughly $1,550 for about 780 square feet, two-bedrooms about $1,856 for roughly 1,150 square feet, and three-bedrooms about $2,306 for roughly 1,580 square feet.
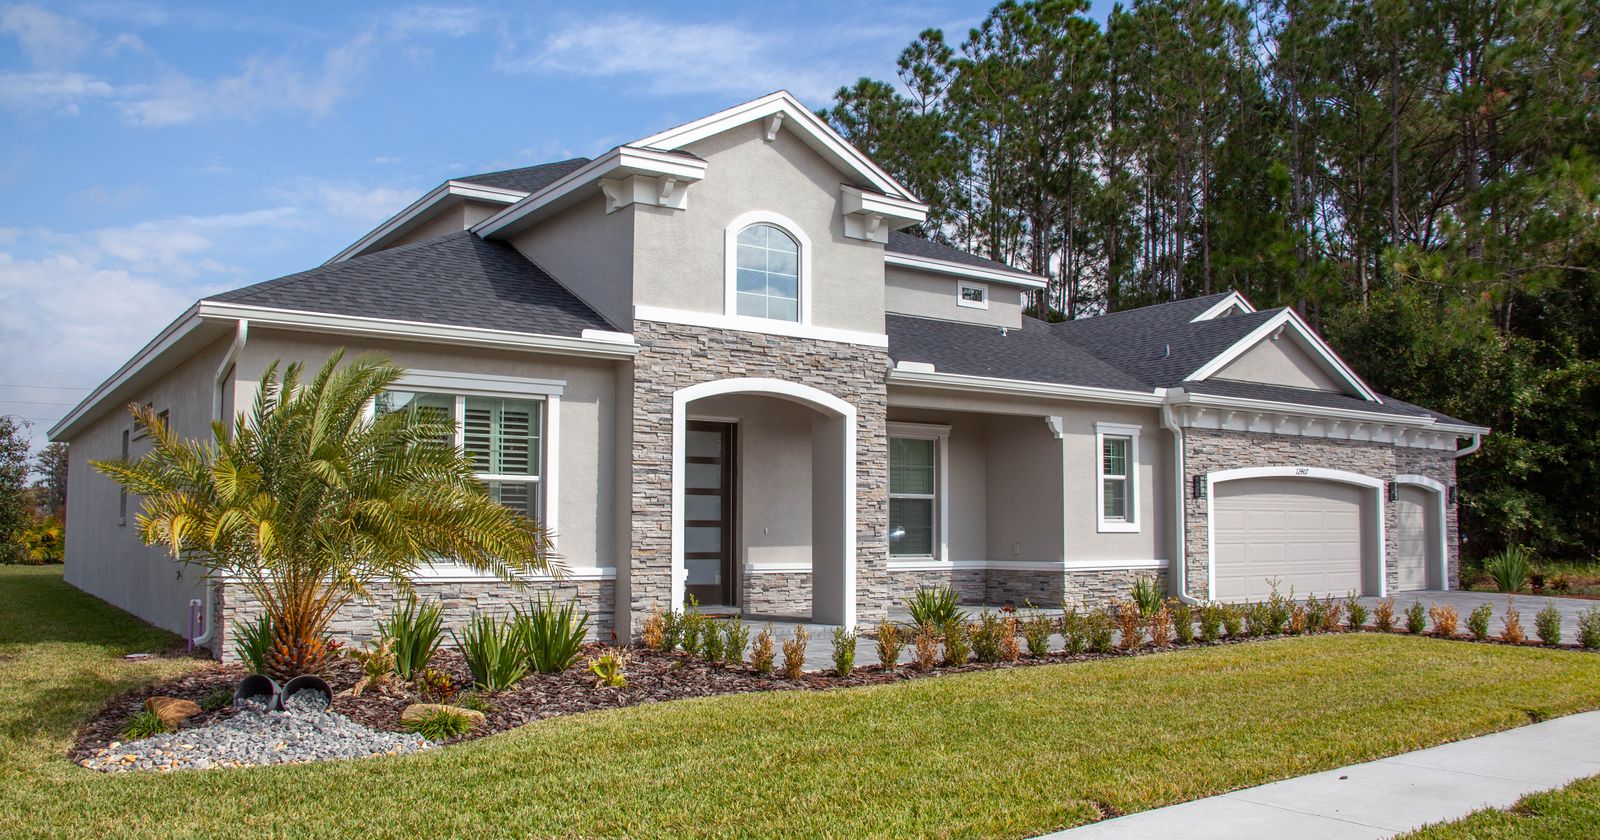
Single-family detached homes — the actual product most investors buy here — price above those apartment averages. A well-kept three-bedroom, two-bath house in a newer St. Cloud community is realistically a $2,300 to $2,500 asset in today's market, with four-bedrooms reaching further. Useful sanity check: HUD's Fair Market Rent for Osceola County currently sits at $1,857 for a two-bedroom and $2,362 for a three-bedroom. When your pro forma rent runs well above FMR, you are underwriting the top of the market, and the top of the market is where days-on-market for rentals stretches out.
The practical vacancy picture is that quality product still leases, but not instantly, and not above ask. Concessions have quietly returned — half a month free, or a waived pet fee — particularly in the newer subdivisions where several builder-owned rentals compete on the same street. At Bella Trae Realty we now underwrite a full month of vacancy per year in St. Cloud rather than the two weeks that penciled in 2023.
The Buy Side Has Softened, and That's Your Leverage
Here is the more interesting half of the report. St. Cloud's for-sale market has cooled materially, and that cooling is worth more to a buy-and-hold investor than another point of rent growth would be.
Median sale price is running roughly $396,000 to $405,000. Inventory stands near 1,332 active listings, up about 6.2% year over year, with roughly 219 new listings added in the most recent thirty-day window — an 11.2% annual increase in new supply. Median days on market has stretched to about 70 days, up from roughly 63. The two numbers that matter most: the median sale-to-list ratio is about 97.3%, and only 7.4% of homes are selling above list, down more than four points year over year.
Translated, that means the typical St. Cloud seller is accepting under ask, more than nine in ten sales are closing at or below list, and sellers are waiting well over two months. That is a negotiating environment. For an investor, basis is the one variable you fully control at acquisition, and right now St. Cloud is handing out room on basis.
Running a Real $400,000 St. Cloud Rental
Illustrative math, stated assumptions, and it is not advice — run your own. Take a $400,000 three-bedroom in a newer St. Cloud community, 25% down, a $300,000 investor loan near 6.9%, renting at $2,400.
- Gross annual rent: $28,800
- Property taxes (non-homestead, ~1.35%): $5,400
- Insurance: $3,200
- HOA: $1,140
- Management at 10%: $2,880
- Maintenance and capital reserve at 5%: $1,440
- Vacancy at 4%: $1,152
Net operating income lands near $13,600, a cap rate of roughly 3.4% on purchase price. Principal and interest on the $300,000 note runs about $1,976 monthly, or $23,700 a year. The property runs roughly $10,000 a year negative on cash flow.
That is the honest answer, and it is why the buy-side softening matters so much. Negotiate the same house to $370,000 with 30% down and the annual shortfall compresses to roughly $6,500. Getting to genuine day-one breakeven at today's rates takes something closer to 50% down, a materially better basis, or a fourth bedroom that supports $2,700-plus. St. Cloud in 2026 is an appreciation, amortization, and tax-treatment play with a stable tenant base underneath it — not a day-one cash-flow play at conventional leverage. Investors who underwrite it as the former do well here. Investors sold on the latter get surprised in year one.
What We're Watching Into Q4 2026
Three variables. First, the new-construction pipeline along Narcoossee Road and Canoe Creek — builder incentives on unsold standing inventory compete directly with your rental, and they are currently the most aggressive we have seen since 2019. Second, insurance renewals, which remain the least predictable line in any Central Florida pro forma and the one most likely to move a marginal deal to negative. Third, Lake Nona and Medical City hiring, which is the single largest driver of St. Cloud tenant demand and the number worth tracking most closely if you own here.
If you are weighing a St. Cloud purchase against a Champions Gate or Davenport short-term rental, the decision is not really about which market is stronger. It is about which risk you are equipped to carry and which one you actually want to manage. Bella Trae Realty underwrites and manages both, and we will tell you plainly when the numbers on a specific address do not work.
Contact Bella Trae Realty today for a submarket-specific rent analysis, a line-by-line review of a St. Cloud or Osceola County deal you are considering, or a straight conversation about property management across Central Florida.
Categories
Recent Posts

GET MORE INFORMATION